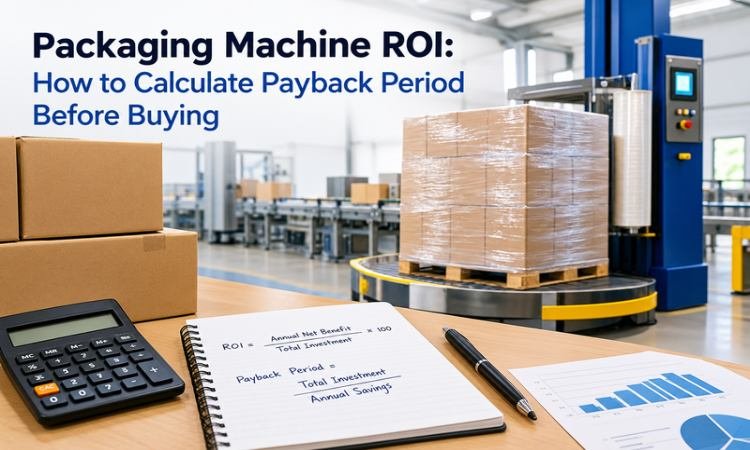
A packaging machine can save manpower, ensure packing uniformity, reduce material consumption, and improve daily production. However, these benefits must outweigh the cost of purchasing, installing, and operating the equipment. Packaging machine ROI indicates the financial return on this investment, while the packaging machine payback period is the amount of time it takes to recover the initial investment through savings and other measurable financial benefits. Both are important for manufacturers, warehouses, and distribution centres when evaluating equipment, considering its operating costs and production requirements, and assessing the overall value of the investment over its useful life. What Does Packaging Machine ROI Mean? ROI (Return on Investment) for a packaging machine measures the financial return generated by the investment made in the equipment. The formula for simple annual ROI is: Simple Annual ROI (%) = Annual Net Financial Benefit ÷ Total Initial Investment × 100 The annual net financial benefit can include measurable savings from: Reduced packaging labour costs Lower material consumption Higher production output, where the additional capacity can be used profitably Reduced packaging-related downtime Less rework and fewer damaged products Other operating cost reductions directly associated with the machine ROI can be used to compare investments, while the payback period provides an estimate of how long it will take to recover the initial investment. These calculations provide a useful starting point for evaluating packaging equipment. However, they are estimates based on the costs, savings, and operating conditions used in the calculation. How to Calculate Packaging Machine Payback Period The basic formula is: Payback Period = Total Initial Investment ÷ Annual Net Savings For a more accurate calculation, first determine the total investment and then estimate the machine’s annual financial benefits after accounting for additional operating costs. Step 1: Calculate the Total Packaging Machine Investment Do not consider only the machine’s quoted purchase price. Depending on the project, the initial investment may include freight, taxes, tooling, and other necessary costs in addition to the following: Cost What to Consider Machine purchase price Quoted equipment cost Installation Installation, commissioning, and setup Electrical or infrastructure work Required power supply, space, or supporting modifications Training Operator or maintenance training, if charged separately Integration Additional equipment or production line integration costs Initial consumables Any required startup materials Freight and other project costs Transportation, applicable taxes, tooling, and other necessary expenses, where relevant For example, if a machine costs ₹8 lakh and installation and related setup costs add another ₹1 lakh, the initial investment is ₹9 lakh, assuming there are no other costs to include. Step 2: Estimate Current Packaging Costs Do not invest in automation without establishing a baseline. Record the costs of your current packaging process for a typical month or year. Include: Number of employees involved in the activity Labour hours Packaging material consumed Output per shift Additional working hours or shifts required because of packaging delays Downtime Rework and damaged products Current maintenance costs for the existing process This step is important because it establishes a baseline against which you can compare the actual operating costs and performance of the packaging machine rather than relying on assumptions. Use consistent measurement periods when comparing the existing process with the proposed machine. For example, compare annual costs with annual costs rather than comparing one month’s savings with a full year’s investment. Step 3: Calculate the Expected Annual Savings Packaging machines can add value in several ways. Labour Cost Savings Automation can potentially reduce labour requirements in a specific packaging application. Calculate the actual annual labour cost reduction resulting from the change. For example: Annual Labour Savings = Monthly Labour Cost Reduced × 12 Do not assume that all current employee salaries will become savings. The actual financial benefit may be different if employees are reassigned to other production tasks. Productivity Gains A machine can package more units in the same amount of time. The financial value comes from the additional productive capacity, provided that the business can use it. For instance, a 20% increase in packaged units does not automatically guarantee a 20% increase in profit. The additional production capacity must be supported by sufficient demand, available storage, adequate upstream production capacity, and a realistic opportunity to generate value from the extra output. Only include productivity gains in the ROI calculation when they can be translated into a measurable financial benefit. Avoid counting the same benefit again under labour savings or reduced downtime. Material Savings In some cases, automation can improve consistency and reduce packaging material waste. Calculate: Annual Material Savings = Annual Material Cost Before Automation − Annual Material Cost After Automation Use measured consumption wherever possible rather than assuming a fixed percentage reduction. The comparison should account for changes in production volume, packaging specifications, and material prices. Otherwise, the estimated savings may not reflect the actual benefit of the machine. Downtime and Rework If manual packaging causes delays, inconsistent packing, or avoidable rework, the financial impact can be included when it can be measured reliably. For example: Annual Downtime Savings = Recoverable Financial Value from Reduced Downtime Be careful with this figure. Lost production should only be counted as a financial benefit when the business can realistically recover that output and generate value from it. For example, reducing downtime may allow a manufacturer to fulfil additional customer orders. However, if the business cannot sell or use the additional output, the reduction in downtime may not translate into an equivalent financial saving. Similarly, avoid counting the same benefit under both downtime savings and productivity gains. A Simple Packaging Machine ROI Example Assume a manufacturer is considering a packaging machine with the following costs and expected benefits: Machine and installation cost: ₹9 lakh Estimated annual labour savings: ₹3 lakh Estimated annual material savings: ₹1.2 lakh Estimated annual financial benefit from reduced downtime: ₹80,000 Additional annual operating and maintenance costs: ₹1 lakh For this example, assume that the ₹9 lakh investment includes all applicable initial project costs and that the listed savings are achievable, measurable, and separate from one another. The expected annual